Hygiene awareness from the Covid-19 pandemic continues to underpin tissue growth, but challenges from regional turbulence remain. Report by Bruce Janda, Senior Consultant, ResourceWise.
When we last visited Türkiye in this column two years ago, its domestic tissue demand appeared to be slowing in the post-pandemic period. Türkiye’s electric grid included coal power resulting in higher carbon emissions compared to other countries. The Ukraine War resulted in stress at the Black Sea entry point through Türkiye. Now the Ukraine War continues while a new Middle East war has brought the country to the periphery of another conflict as it shares borders with Iran, Iraq, and Syria.
Türkiye has become a major tissue exporting powerhouse while domestic tissue demand at about 6kg per capita consumption has lagged Western Europe (16kg) and North America (26kg). Türkiye’s tissue export business continues to be strong but new capacity additions planned for Saudi Arabia and others in the Middle East could displace some business.
Türkiye has very limited virgin pulp capacity that is used on site at Packaging and Specialty grade mills. There is no Market Pulp production. Its tissue business depends mostly on imported virgin pulp for tissue exports. This makes Türkiye’s tissue exports subject to market pulp price swings while other tissue exporting countries like Brazil and Indonesia have mostly internal pulp supplies.


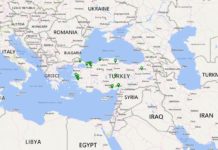
Türkiye has 14 tissue sites as shown on the map in Figure 1. The blue pins represent non-integrated sites using market pulp and the green pins represent tissue production sites integrated with recycled fibre processing. These sites support a total of 26 operating tissue machines, spread through the western half of the country near the Black Sea and Mediterranean coasts.
Türkiye’s population growth has slowed since 2018 as shown in the blue line in Figure 2. The economy has expanded since 2020 as shown in the GDP/capita gold bars. Note that this chart is adjusted for purchasing power parity (PPP). Figure 2 is relatively supportive of developing domestic tissue demand.
Figure 3 shows that inflation peaked at almost 80% in 2022 and is coming down below 50%. This price excursion starting with Covid-19 has placed a lot of stress on Türkiye’s tissue consumers. Unemployment has returned to the typical range below 10% last seen in 2011-2013. The result is a slightly unfavourable environment for further development of domestic tissue consumption. News reports suggest that domestic consumers have increasingly turned to private label tissue products to reduce costs. A positive note for domestic consumption is the increase seen in paper towel consumption that started during the pandemic but now continues to grow.
Tissue export and import trends are shown in Figures 4 and 5. Exports have grown up to the last data point for 2025. This could be a data timing issue as trade reporting tends to run late. The United Kingdom continues to lead the chart with smaller amounts to the United States, Romania, Bulgaria, and Greece. We have already seen the new capacity forecasted for the United Kingdom and Saudi Arabia. The all-others bar segment at the top of each bar is growing and represents a group of export destinations that each have 5% or less share of the total. This diverse group is growing to almost half of the total export volume. Türkiye is gaining new fragmented share while losing volume at traditional customers. This may indicate more competition from other tissue exporters.
Figure 5 shows the tissue imports trend on the same scale as the exports to exhibit the large imbalance of tissue trade. Tissue exports are about 50 times greater than imports. However, Türkiye’s tissue production is about 10 times the export amount. If exports were to continue to shrink, domestic demand increases will be needed to keep the system balanced.
Several older commercial and consumer tissue machines were taken out in 2024 as shown in Figure 6. New consumer tissue capacity is planned to come online in 2026 through 2028. This will probably drive more capacity balancing.
Türkiye’s tissue mills are about 80% non-integrated and dependent on imported market pulp as shown in Figure 7. The remainder are at least partially integrated with recycled fibre resulting in a lower cost structure. This configuration offers good product flexibility to meet expectations of importing companies but leaves 80% of Türkiye’s production at risk to current market forces lifting raw material and transportation costs.
Figure 8 provides a more detailed view of fibre usage by tissue product grade and format. Consumer bath is the largest category with greater volume than consumer facial and consumer towel added together. Eucalyptus pulp is used in most consumer products, bath, facial, and towel, but not in consumer napkin. Commercial grade products represent a much smaller volume than retail. Commercial fibre mixes include recycled fibre but not at a rate greater than in the retail products.
A comparison set was selected from potential tissue export competitors Brazil and Indonesia with strong fibre cost position. Saudi Arabia has embarked on a tissue production building program and could threaten Türkiye’s business in the Middle East. The United Kingdom has been a long-term customer of Türkiye’s tissue that appears to be reinvesting in tissue production.
This comparison group allows us to benchmark the average quality of Türkiye’s tissue machine fleet. Figure 9 charts the tissue machine fleet averages using bubble charts to compare tissue-machine quality, with bubble size indicating production capacity. The X-axis shows average technical age. The Y-axis plots average machine speed. Machine speed not only provides more production from the machine and crew, but it also indicates the type of drying equipment required to handle the capacity. These factors will be seen in Figure 11 in the tissue machine viability comparisons.
Figure 10 shows how sharply tissue-production costs vary across Türkiye’s comparison group based on potential tissue export competitors, with each bar measuring average cash cost per ton and its width reflecting production capacity. Indonesia and Brazil have the low-cost position and over half of the total tissue production included in the total comparison group. The United Kingdom has the high-cost position, but Türkiye is not too far away while Saudi Arabia has lower costs not much different than Brazil.
The stacked bars in the chart allow a more detailed view of cost pressures. The bottom two bar segments represent fibre costs to integrated mills and purchased market pulp. Türkiye has the highest average cost in this area. The yellow bands across the bars represent average energy costs. Here we see the United Kingdom’s energy cost issues in the size of the impact on average tissue costs. The UK also has higher overhead costs than the sum of all the others. Türkiye’s overall unfavourable tissue production cost position is a risk.
Figure 11 shifts the comparison from immediate cash costs to a broader test of long-term competitiveness, measuring the average viability of tissue machines across several countries. The FisherSolve viability module factors in estimated capital requirements, production costs, machine size, technical age, local economic risk by grade, internal company risk, manufacturing competitiveness, tons produced per unit of trim and export fees. Taken together, those indicators offer a five-year view of which tissue fleets are best positioned to compete.
Viability risk is expressed as an index with higher numbers indicating higher risk. All of the countries’ tissue machine fleets in this plot are ranked as moderate viability but there are some differences. Türkiye’s average tissue machine is rated the highest viability (lowest index score) while the UK is rated weakest. Looking at individual bar segments, the UK and Saudi Arabia rank as requiring more capital spending, but their announced new capacity has yet to come online to move the score. Both the UK and Türkiye have the highest cost positions as seen in Figure 10. Indonesia shows a high risk due to its many older tissue machines in spite of newer construction at integrated sites.
Figure 12 shows a focus on energy costs per ton of the comparison set. This time the chart breaks energy costs down further, from fuel, steam, and grid power to internally generated versus purchased steam and electric power. Direct fuel onsite is broken down into oil versus gas. These figures were measured in mid-2026, as the Gulf war energy costs started to take effect and could shift significantly as regional energy markets respond. Indonesia holds the lowest energy cost position, and the United Kingdom has the highest cost position. Indonesia is using more oil as the onsite fuel compared to others. Purchased electricity is a much higher cost for the UK and Saudi Arabia. Additionally, the much higher costs in the UK are also driven by gas fuel and steam generated onsite. These costs have continued to increase and where they will land is not clear.
Figure 13 displays the energy cost breakdown into actual heat or energy units used per ton. This eliminates local price advantages or disadvantages for a direct engineering view of energy efficiency. The differences seen in the price-based chart are significantly reduced. The UK still shows much higher gas and oil consumption but many of the other differences appear to be more price determined. These energy charts should be seen as a snapshot from this summer, and prices and energy mix can be expected to evolve throughout the energy crisis.
Figure 14 adds an emissions lens to the regional comparison, showing Scope 1 emissions from onsite fuel use in red and Scope 2 emissions from grid electricity in tan, each measured per ton of finished tissue. Scope 2 results depend heavily on the carbon intensity of the local power grid. Indonesia benefits from a relatively low-carbon grid and lower fuel-related emissions, helped by a larger share of tissue machines located at integrated pulp sites where heat and electricity can be generated from carbon-neutral biomass. The underlying energy units detail is shown in Figure 13.
Saudi Arabia has the largest carbon footprint due to high carbon fuel on site and purchased electricity carbon content. Türkiye is in a middle range with the UK and Indonesia and Brazil continues to enjoy lower carbon content energy.
Türkiye’s tissue industry continues to be export-focused but strong global players are growing, and export customer regions (Middle East) and the UK have tissue production growth plans. Türkiye’s domestic tissue demand has grown slowly as consumers struggled with very high inflation during several decades of tissue production capacity build-out. Domestic consumers have been looking to private label products. A bright spot in the development of consumer demand is the consumer towel segment that developed during the pandemic to clean and dispose of household messes. Türkiye has a very low commercial tissue demand that is surprising given the relative industrial and economic development. Both consumer towels and the commercial tissue segments appear to be opportunities for developing further domestic demand to back up the export tissue business.
Global volatility is intensifying those pressures. Shifts in fibre prices, exchange rates, energy markets and environmental regulation are reshaping the economics of tissue production across the region. Türkiye’s mills are likely to see further ownership changes and consolidation, while new tissue making investment in neighbouring countries could alter the country’s import and export flows in the years ahead.
Key points and conclusions
- Türkiye is a tissue export powerhouse, but the export base is narrowing in quality: traditional customers are shrinking while a fragmented “all others” group now accounts for almost half of export volume.
- Domestic demand remains the weak link at about 6kg per capita, far below Western Europe (16kg) and North America (26kg), after years of inflation that peaked near 80% in 2022 and pushed consumers toward private label.
- Consumer towel and commercial tissue are the two clearest domestic growth openings – towel demand built during the pandemic and continues to grow, and commercial demand is unusually low for an economy at Türkiye’s level of development.
- Fibre position is the structural vulnerability: roughly 80% of the 14 sites and 26 machines are non-integrated with no market pulp production in-country, leaving exports exposed to imported pulp price swings that Brazil and Indonesia are insulated from.
- Cost position is unfavourable. Türkiye carries the highest average fibre cost in the comparison set and sits close to the high-cost United Kingdom overall, while Indonesia and Brazil hold the low-cost position and Saudi Arabia is not far behind them.
- Machine quality is a genuine strength — Türkiye’s fleet rates the best average viability in the comparison group, ahead of the UK, Saudi Arabia, Brazil, and Indonesia.
- Energy is now a live variable. Measured mid-2026 as Gulf war costs began to bite, the UK carries the highest energy cost and Indonesia the lowest; on a physical energy-units basis most of those gaps narrow, confirming the spread is largely price-driven and unsettled.
- On emissions, Türkiye sits mid-pack with the UK. Saudi Arabia has the largest footprint, while Indonesia and Brazil benefit from lower-carbon grids and biomass energy at integrated sites.
- New capacity in Saudi Arabia, elsewhere in the Middle East, and the United Kingdom threatens Türkiye’s export outlets over 2026–2028, so building domestic demand is the practical hedge.
- Expect further consolidation and ownership change among Türkiye’s mills as fibre, currency, energy, and environmental costs reshape regional tissue economics.